
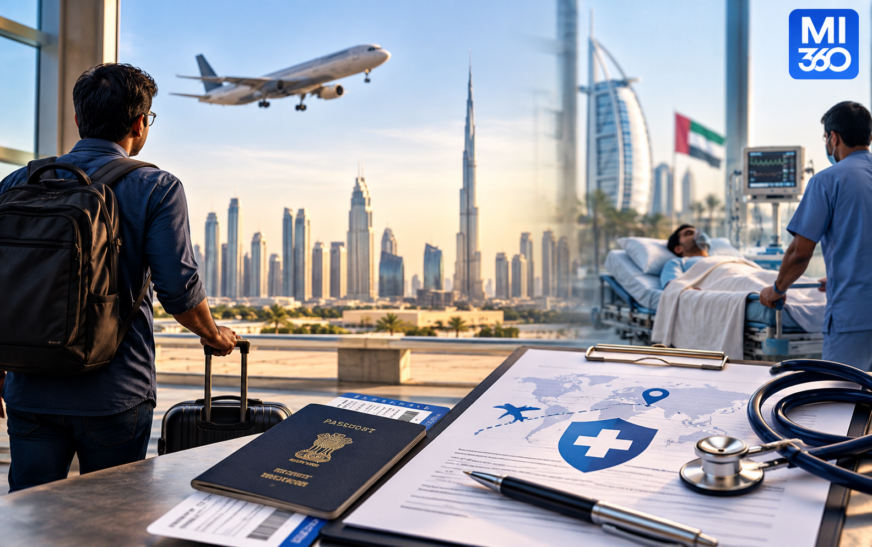
Following recurring cases of Indian travellers and expatriates facing crippling hospital bills during health crises in the United Arab Emirates, Indian diplomatic missions have issued an urgent advisory. Authorities are urging all visitors and residents to secure comprehensive UAE medical insurance for Indians that explicitly includes medical repatriation coverage.
Indian diplomatic missions in the United Arab Emirates have issued an urgent public advisory urging Indian nationals visiting or residing in the country to secure comprehensive health coverage before travel. Reported on October 28, 2026, by NewsOnAir, ANI, and NDTV, the directive comes after multiple medical emergencies left uninsured or underinsured Indian citizens burdened with massive hospital bills. Highlighting the financial distress faced by affected families, the missions specifically advised travellers to ensure their UAE medical insurance for Indians includes adequate emergency treatment limits and dedicated repatriation cover.
What Happened: Diplomatic Missions Flag Rising Uninsured Medical Crises
In a coordinated outreach targeting both short-term travellers and the large resident diaspora, the Indian missions in the UAE warned that sudden illnesses and accidents abroad can rapidly escalate into financial emergencies when travellers lack valid coverage. According to reporting by Moneylife and ANI, diplomatic officials have repeatedly encountered cases where Indian nationals required intensive hospital care in the UAE but held either no insurance policy or basic coverage that fell far short of actual inpatient charges.
To prevent families from falling into severe debt or relying on emergency consular assistance and community crowdfunding, the advisory outlines two essential precautions for Indian nationals:
- For Tourists and Short-Term Visitors: Every Indian national travelling to the UAE on a tourist, visit, or short-term business visa is strongly advised to purchase an international travel medical insurance policy with an adequate sum insured prior to departure.
- Mandatory Focus on Repatriation Cover: Travellers and expatriates must verify that their policy explicitly covers medical evacuation and repatriation—both for transporting a critically ill patient back to India for continued care and for the repatriation of mortal remains in the event of death.
- For Expatriate Residents: Indians living and working in the UAE are urged to ensure their mandatory residency health insurance remains active at all times, particularly during job changes, visa renewals, or sponsor transitions.
Background and Context: Why Coverage Gaps Persist in the India–UAE Corridor
The United Arab Emirates is home to one of the largest Indian expatriate communities globally and ranks as the top international destination for Indian leisure travellers, business visitors, and job seekers. While healthcare infrastructure in cities such as Dubai and Abu Dhabi is world-class, medical treatment is predominantly private and billed at international rates. Intensive care unit (ICU) admissions, cardiac interventions, trauma surgeries, or neonatal care can quickly run into tens of thousands of UAE dirhams (equivalent to several lakhs or even crores of Indian rupees).
Although the UAE enforces mandatory employer-sponsored health insurance for resident visa holders, three vulnerable groups frequently fall through the cracks:
- Elderly Parents and Visiting Relatives: Senior citizens visiting children working in the UAE often travel without pre-existing disease (PED) coverage or purchase bare-minimum policies with strict sub-limits on cardiac and age-related emergencies.
- Job Seekers on Visit Visas: Individuals entering the UAE on short-term visit visas to look for employment often let their initial short-duration travel insurance expire while extending their stay, leaving them completely exposed during the transition before an employer visa is issued.
- Workers Between Employment Sponsors: Expatriates whose residency visas are cancelled or under dispute during a job switch can experience temporary lapses in their local health cards.
Why This Matters for Policyholders and the Insurance Industry
The diplomatic advisory carries immediate practical consequences for travellers, insurance intermediaries, and product designers in India’s non-life and health insurance market:
- Policyholders and International Travellers: Many Indian travellers treat travel insurance as a visa-processing formality rather than a financial protection tool, opting for the cheapest plan bundled by an online travel aggregator (OTA). In high-cost medical jurisdictions like the UAE, low sum-insured plans (such as USD 10,000 or USD 25,000 limits with heavy room-rent sub-limits) can be exhausted within a few days of critical care.
- The Critical Role of Repatriation Clauses: Commercial stretcher evacuation or air ambulance transport from the UAE to an Indian city—accompanied by medical personnel and life-support equipment—costs substantially more than standard commercial airfare. Similarly, legal clearance, embalming, and air cargo repatriation of mortal remains involve significant logistical expenses that standard domestic health policies do not cover.
- Travel Agents, Brokers, and InsurTech Platforms: Intermediaries selling UAE flight tickets and visa packages play a frontline role in risk education. Highlighting the Indian Missions’ October 2026 advisory gives brokers and digital platforms a clear mandate to discourage underinsurance and explain policy exclusions transparently.
- Indian General and Stand-Alone Health Insurers (SAHIs): Domestic insurers offering international travel policies and global health add-ons have an opportunity to design Gulf-specific travel products featuring higher base medical limits, transparent pre-existing illness riders for visiting parents, and seamless cashless hospital networks across UAE emirates.
Industry Analysis: Closing the Protection Gap Between Visa Rules and Real Risk
From an insurance business analyst perspective, the UAE advisory highlights a recurring mismatch between minimum visa compliance insurance and actual medical cost inflation.
When travellers buy basic entry-level travel cover bundled automatically with a tourist visa, those policies are often structured with tight caps on emergency outpatient care, zero coverage for acute flare-ups of pre-existing conditions like diabetes or hypertension, and high co-payments for senior citizens. When a major medical event occurs—such as a stroke or cardiac arrest—the insurer may validly reject the claim under a pre-existing condition exclusion, leaving the family to negotiate directly with a foreign hospital.
Furthermore, consular budgets maintained by Indian missions abroad (such as the Indian Community Welfare Fund) are designed to assist destitute workers in extreme distress, not to serve as an alternative to private travel medical insurance for general visitors. By explicitly naming medical repatriation cover in the October 28 advisory, Indian authorities are signalling that travellers must shift from buying the cheapest compliant certificate to selecting comprehensive risk protection.
What Happens Next?
While the October 28 communication from the Indian Missions in the UAE is an official advisory rather than a newly enacted statutory travel ban, travellers should closely monitor both Indian consular updates and UAE Federal Authority for Identity, Citizenship, Customs and Port Security (ICP) visa entry guidelines. Travel agencies and visa facilitators operating between India and the Gulf are expected to tighten client advisories ahead of the peak winter travel season (November to February), when tourist and family visits to Dubai and Abu Dhabi surge.
Ultimately, the message from Indian officials in the UAE is straightforward: the cost of a comprehensive international travel policy with repatriation benefits is a tiny fraction of a single day in an overseas intensive care unit. Checking policy limits, pre-existing disease clauses, and repatriation benefits before boarding a flight is the only reliable safeguard against a medical crisis turning into permanent financial ruin.