
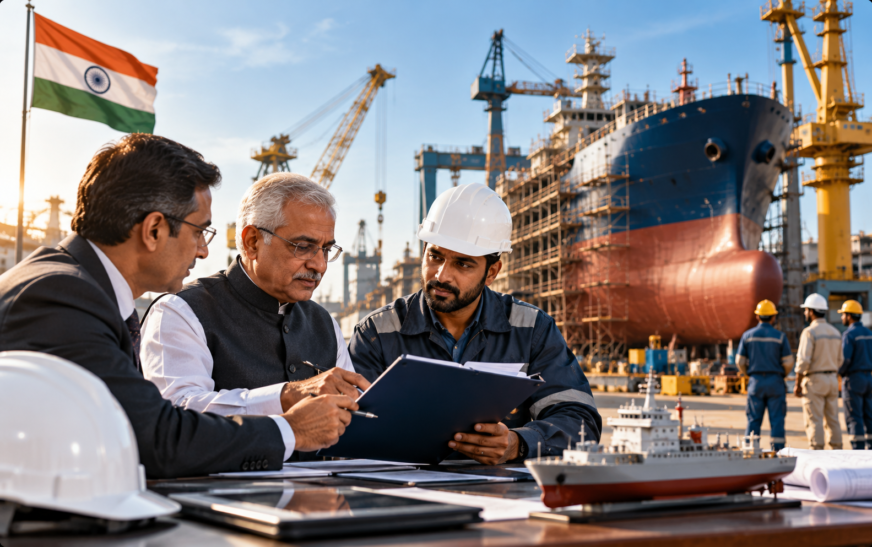
India’s Ministry of Ports, Shipping and Waterways has rolled out two government-backed credit risk insurance products to protect domestic shipyards against buyer defaults and delayed milestone payments. Backed by a ₹1,443-crore sovereign corpus and underwritten by ECGC and New India Assurance, the policies aim to de-risk multi-year vessel construction.
India’s Ministry of Ports, Shipping and Waterways (MoPSW) has introduced two specialised credit risk insurance for shipbuilders to shield domestic shipyards from buyer defaults, delayed milestone payments, and working-capital disruptions. Announced by Union Shipping Minister Sarbananda Sonowal at the 21st Maritime State Development Council (MSDC) meeting in Mumbai, the twin policies divide coverage between export vessel contracts and domestic orders. Underwritten by state-owned insurers ECGC Ltd and The New India Assurance Co. Ltd., and backed by a ₹1,443-crore (approximately USD 152 million) central corpus, the scheme provides both premium subsidies for shipyards and direct claim-settlement support for insurers.
What Happened: Two Tailored Policies for Export and Domestic Yards
Constructing commercial vessels is a capital-intensive process that spans several years, leaving shipyards financially vulnerable if a buyer delays stage payments or cancels an order mid-build. To address this exposure, the ministry launched two distinct insurance instruments under the National Shipbuilding Mission, as reported by ETSupplyChain and The Economic Times:
- Shipbuilding Project Credit Risk Insurance Policy (SbPCP): Designed and administered by state-owned export credit insurer ECGC Ltd, this policy covers Indian shipyards building vessels for overseas shipowners and export markets.
- Business Credit Shield Policy – Shipbuilders (BCSPS): Developed by public-sector general insurer The New India Assurance Co. Ltd., this product protects shipyards executing vessel orders for domestic buyers within India.
Speaking at the Mumbai launch, Union Minister Sarbananda Sonowal stated:
“With these new insurance policies, we are stepping in to give them a real safety net. We want our shipyards to focus on what they do best, building world-class vessels, without the fear of delayed payments or sudden global market shifts holding them back.” — Sarbananda Sonowal, Union Minister of Ports, Shipping and Waterways (via PTI / The Economic Times)
According to maritime publication Splash247, the credit risk backstop is supported by an allocation of ₹1,443 crore (INR 14.43 billion, or roughly USD 152 million). Rather than operating as a purely commercial line where shipyards bear high market premiums, the central government will subsidise the policy premiums and provide a financial backstop directly to the insurers if shipyards file eligible claims.
Background and Context: Inside the ₹19,989-Crore Shipbuilding Push
The rollout of specialised credit risk insurance operationalises a key pillar of the Shipbuilding Development Scheme (SbDS). Approved by the Union Cabinet in September 2025, the ₹19,989-crore (USD 2.1 billion) SbDS forms part of a broader ₹69,725-crore maritime and shipbuilding package aimed at expanding India’s commercial fleet and competing with established Asian shipbuilding hubs in China, South Korea, and Japan.
According to official MoPSW Guidelines for Shipbuilding Risk Coverage under SbDS, the operational architecture works through a three-tier structure:
- Corpus and Implementation Agency: The government-allocated credit risk corpus is channelled through Sagarmala Finance Corporation Limited (SMFCL), which serves as the designated Implementation Agency (IA).
- Contract-Specific Customisation: Unlike standard trade credit policies designed for short-term goods export, the guidelines mandate that policies be structured around shipbuilding cash flows—specifically advance payments, keel-laying and launch milestone payments, delivery-linked instalments, and retention money. Modular options under the framework also encompass pre-shipment, post-shipment, and vendor default coverage.
- Nominal Premiums: Because the underlying risk corpus is funded by the Government of India through SMFCL, the nominated public-sector insurers are mandated to keep premium rates nominal for participating shipyards.
The insurance launch was paired with broader regulatory and infrastructure steps at the 21st MSDC meeting—the council’s first session since becoming a statutory consultative body under the Indian Ports Act, 2025 (notified on May 15, 2026). Alongside pushing for port-linked industrial clusters and multimodal connectivity, the ministry released a Ready Reckoner for implementing the One Nation One Port (ONOP) framework to harmonise customs, health, and security clearances across major and non-major ports.
Why This Matters for Insurers, Lenders, and Shipbuilders
For India’s commercial insurance and project finance ecosystem, a sovereign-backed credit risk shield alters how maritime construction risks are underwritten and funded:
- Domestic Shipyards and Ancillary Suppliers: A single delayed instalment from a shipowner can freeze a shipyard’s working capital, delaying steel procurement and subcontractor payments. Credit risk cover ensures cash-flow continuity across multi-year build schedules.
- Commercial Banks and Project Financiers: Indian banks have historically been cautious about extending working-capital credit and refund bank guarantees to shipyards due to the risk of buyer insolvency during global freight downturns. An insurance policy underwritten by ECGC or New India Assurance acts as strong collateral enhancement, lowering credit risk weightings for lenders.
- Public-Sector Underwriters (ECGC & New India Assurance): Writing large-ticket project credit default risk on multi-million-dollar vessels would normally expose an insurer’s balance sheet to severe concentration and catastrophe-like credit losses. By pairing insurer administration with a government-funded corpus via SMFCL, New India Assurance and ECGC can offer specialised cover without straining their standalone solvency margins.
- Commercial Insurance Brokers: Brokers advising heavy engineering, defense, and commercial shipyards now have a dedicated sovereign-backed credit wrap to pair alongside traditional Builder’s Risk (Marine Hull Construction) and surety bond programmes.
Industry Analysis: Bridging the Financing Gap in Heavy Manufacturing
From an insurance business analyst perspective, India’s intervention targets one of the hardest-to-place risks in commercial underwriting: long-tail contract frustration and buyer default.
In standard commercial insurance, Indian shipyards can readily buy Marine Builder’s Risk insurance to cover physical damage to a vessel under construction (such as fire,dry-dock collapse, or launch mishaps). However, private trade credit insurers globally are often reluctant to offer multi-year, non-cancellable credit limits covering stage-payment defaults on bespoke capital goods like ships—especially during volatile shipping cycles when freight rates and vessel valuations swing sharply.
By splitting the mandate between ECGC (which already possesses deep underwriting expertise in sovereign, political, and overseas buyer risk) and New India Assurance (India’s largest non-life insurer with an extensive domestic corporate network), the government avoids building a new bureaucracy from scratch.
However, the practical effectiveness of the scheme will depend on two operational factors:
- Speed of Interim Claim Settlements: When a vessel buyer defaults or delays a milestone payment, a shipyard faces an immediate liquidity crunch. How quickly New India Assurance, ECGC, and SMFCL assess claims and disburse funds will determine whether the policy prevents construction halts in real time.
- Underwriting Buyer Quality: Even with a ₹1,443-crore government backstop, underwriters will need clear risk-selection guardrails so that subsidised insurance does not encourage shipyards to sign contracts with undercapitalised or speculative vessel buyers.
What Happens Next?
Following the formal launch of SbPCP and BCSPS at the Mumbai MSDC session, domestic shipyards executing or bidding for commercial orders can begin onboarding under the scheme rules administered by SMFCL, ECGC, and New India Assurance. Industry stakeholders will closely watch initial policy uptake by major public and private yards—such as Cochin Shipyard and other coastal builders—as well as how coastal states execute the MSDC’s parallel directives on land allocation and port-linked shipbuilding clusters aligned with the Maritime India Vision 2030 (MIV 2030) and Maritime Amrit Kaal Vision 2047 (MAKV 2047).
Ultimately, while cheaper land and faster port clearances build physical capacity, financial de-risking is what closes orders. If executed with streamlined underwriting and prompt claims support, India’s twin credit risk policies could remove a longstanding financial barrier keeping domestic shipyards from competing for large global fleet contracts.